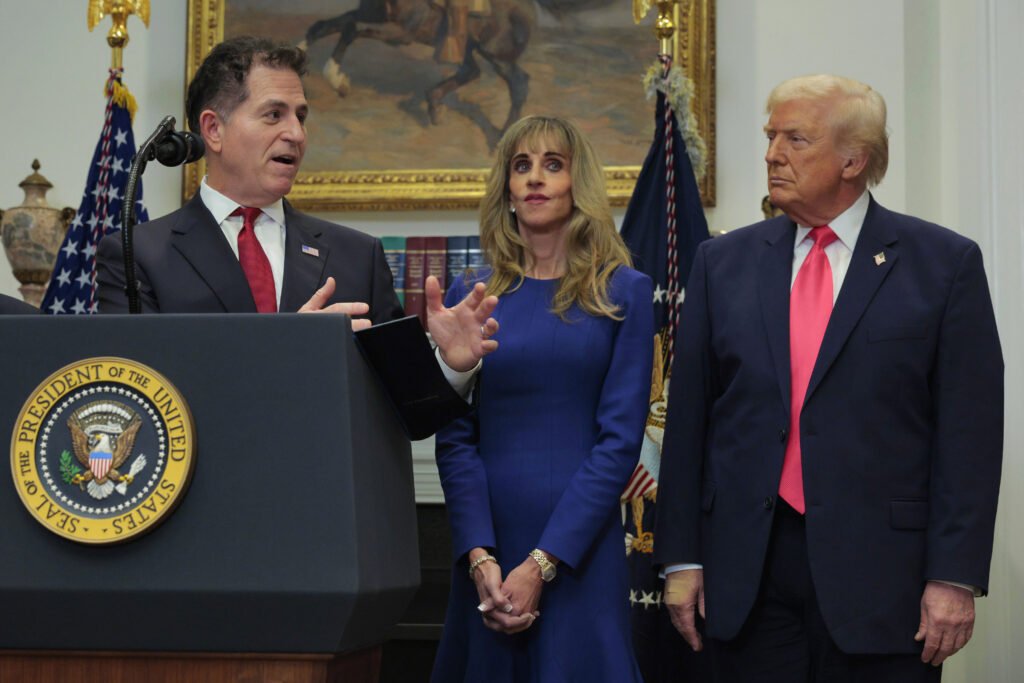
Michael Dell is backing a proposal that could give Trump Account holders the ability to invest in individual company stocks, saying greater investment choice could make the new savings program more appealing and potentially encourage long-term wealth building.
Trump Accounts were established as a new savings and investment vehicle aimed at helping families build financial resources for children. Rather than leaving contributions in cash, the accounts are designed to place money into investments, allowing funds to potentially grow over many years.
The discussion surrounding individual stocks has become one of the more notable issues connected with the program. Dell, the founder and chief executive of Dell Technologies, has defended the idea of allowing account holders to have a more direct role in deciding where their money is invested.
Supporters of the proposal argue that giving families access to individual companies could make investing easier to understand and more engaging. Many consumers already recognize major corporations through the products and services they use, and supporters believe that familiarity could encourage greater interest in financial markets.
The approach would also provide investors with more control than a system limited to broad investment funds. Individuals could potentially choose companies they believe have strong long-term prospects, giving them a direct connection to the businesses in which their savings are invested.
However, the proposal also comes with potential risks. Individual stocks can experience significant price swings, and concentrating money in a limited number of companies can expose investors to larger losses. If a particular business encounters financial difficulties or suffers a major decline in its share price, investors holding that stock could see the value of their accounts fall sharply.
Diversification is therefore an important part of the debate. Holding a broad collection of companies can reduce the impact of poor performance from any single business. Critics of expanded individual-stock access argue that this approach may be particularly important for accounts intended to help secure a child’s financial future.
Supporters counter that Trump Accounts are designed with a long investment horizon. Because the money may remain invested for many years, investors could have more time to withstand periods of market volatility. Nevertheless, a long time frame does not completely remove the risks associated with individual-company investments.
The discussion also reflects a broader effort to introduce Americans to saving and investing at an earlier age. Starting to invest early can provide more time for potential returns to compound, making even relatively modest contributions potentially more valuable over the long term.
Financial education could become another important part of the program. Giving families greater investment responsibility could encourage parents and children to learn about companies, stock markets, risk and the importance of maintaining a long-term strategy.
Much will depend on the final rules governing Trump Accounts. Questions surrounding eligible investments, contribution limits, fees, diversification requirements and investor protections could all influence how the program operates.
Dell’s support adds a significant business voice to the debate over how much freedom should be available within the accounts. His position reflects the argument that individual-stock options could provide flexibility and encourage greater participation in investing.
As policymakers continue shaping the details of Trump Accounts, the question of investment choice is likely to remain central. The eventual rules will determine whether families can select individual companies, rely primarily on diversified investments, or have access to a combination of both approaches.
You can watch the video below